
Day Porter Service · Miami-Dade
Know What Your Day Porter Vendor Should Cover Before You Sign
A practical guide for Miami-Dade property managers reviewing day porter contracts, certificates of insurance, and vendor paperwork. Start with a free, confidential first consultation with no obligation to continue.
Key Items to Review in a Day Porter Vendor's Insurance
Coverage Types Named in the Contract
Compare the insurance types your contract lists, such as general liability, workers' compensation, and commercial auto when vehicles are used, with what the vendor provides.
Certificate vs. Policy
A certificate of insurance summarizes a policy. When a contract term depends on a specific coverage detail, ask for the policy or endorsement itself.
Limits and Named Insureds
Confirm that coverage limits match your contract and that the named insured matches the company you are hiring.
Additional Insured Language
If your contract requires your property to be listed as an additional insured, verify that the endorsement says so in writing.
Current Dates
Check policy effective and expiration dates so coverage stays in place for the full length of the service agreement.
By Ryan Jurney · Published November 2, 2026
Day porter vendor insurance in Miami-Dade should cover general liability, workers’ compensation for staff, and commercial auto when workers drive for the job. The vendor should also show current registrations and written proof of coverage before work starts. This guide explains each item in plain words, so you can review paperwork you did not prepare.
If you're reviewing a specific day porter proposal for a South Florida building, our team can walk through it with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why a Day Porter Vendor’s Paperwork Matters to a Miami-Dade Building
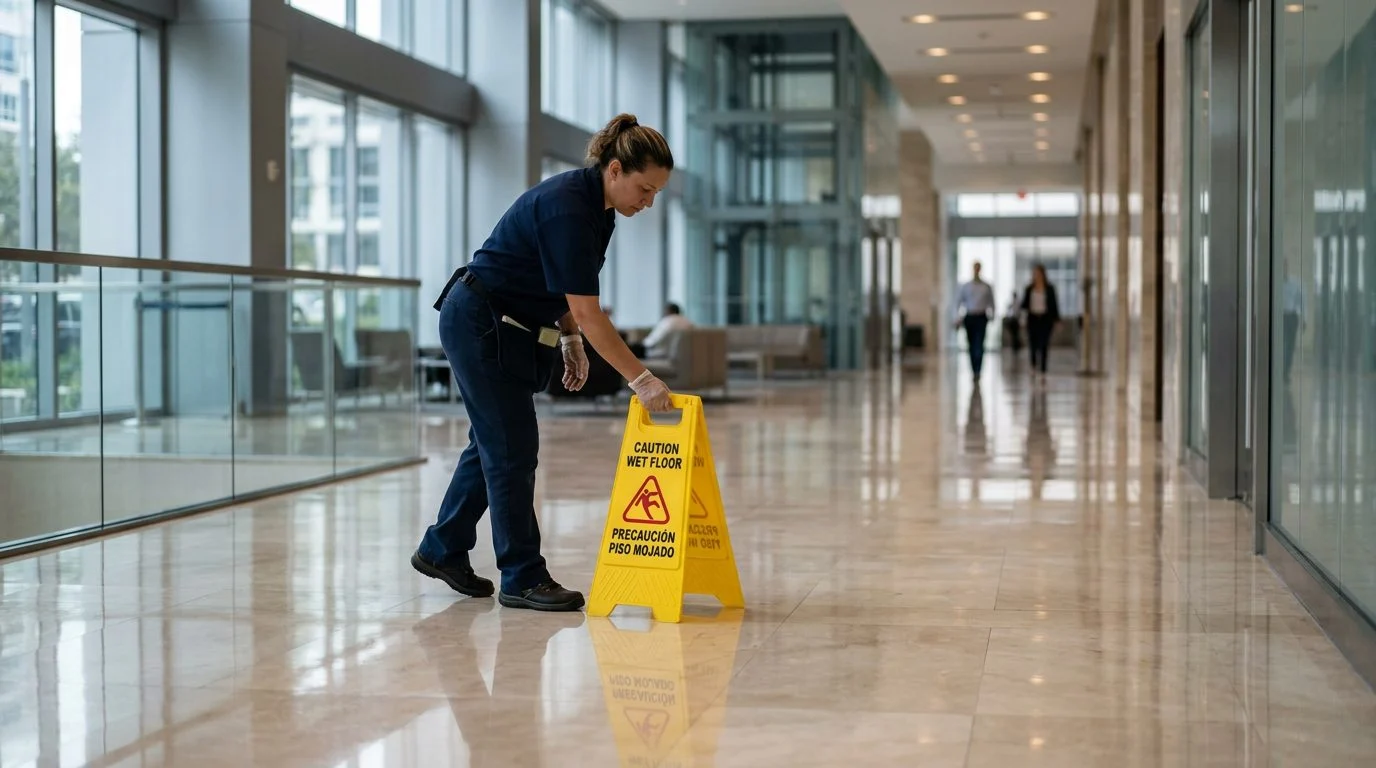
The vendor’s paperwork matters to the owner, the association, and tenants because a day porter works inside occupied space. Day porter staff clean lobbies, restrooms, and common areas while people are in the building. A spill, a fall, or a chemical mishap can affect anyone nearby.
This setting is common across Miami-Dade. Condominiums, office buildings, medical offices, and mixed-use properties in areas such as Brickell, Coral Gables, and South Beach often use day porter service.
When something goes wrong, paperwork shows who is responsible and what coverage is in place. A worker can get hurt. A visitor can slip. A cleaning product can damage a finish. The certificates, registrations, and signed agreement answer those questions before a problem starts.
This page covers the core coverages, business registrations, how to read a certificate of insurance, and the questions to ask before you sign.
The Core Insurance Coverages a Day Porter Vendor Should Carry
Most day porter contracts call for general liability insurance, workers’ compensation, and commercial auto coverage when vehicles are used.
General liability insurance generally addresses third-party injury or property damage tied to the vendor’s work on site. A visitor who slips on a freshly mopped floor is one example. Ask for the limits in writing.
Workers’ compensation insurance covers the vendor’s own employees who are hurt on the job. Florida law requires an employer covered by the workers’ compensation chapter to secure payment of compensation to its employees, under Fla. Stat. § 440.10.
If an employer fails to secure that coverage, an injured worker may choose to claim compensation or file a lawsuit for damages, under Fla. Stat. § 440.11. That choice changes how an injury claim can unfold, so the building owner should care.
Whether a specific vendor must carry workers’ compensation depends on the facts, such as how many people work for it and how they are classified. Ask for proof rather than accepting a verbal answer.
Commercial auto coverage applies when staff drive vehicles to carry supplies or equipment, or to travel between buildings. A vendor that moves crews across sites should show it.
Limits matter too. A limit that fits a small office may not fit a large tower. Check the limits against the size and type of your property instead of assuming they are enough.
Business Licensing and Registrations to Confirm
Ask for current proof that the vendor is registered to do business under the exact name on its contract.
If a vendor uses a trade name, Florida’s Fictitious Name Act applies. It covers any name used in Florida other than the person’s legal name, under Fla. Stat. § 865.09.
Registration under that act is for public notice only. It does not give the registrant ownership rights in the name.
Out-of-state vendors have an extra step. A foreign corporation may not transact business in Florida until it obtains a certificate of authority from the state, under Fla. Stat. § 607.1501.
Work across Miami-Dade can involve more than one city or county. Ask which local registrations or business tax receipts apply to each property. Ask for copies with issue or renewal dates.
Finally, match the names. The legal name on the registration, the contract, and the certificate of insurance should all point to the same company.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How to Read a Certificate of Insurance Step by Step
A certificate of insurance is a short summary. It lists who is insured, which policies apply, their dates, and their limits.
- Named insured. Confirm the named insured matches the company that will sign. A different name is a question to resolve before you sign.
- Dates. Check that the effective and expiration dates cover the full contract period. A certificate that expires in June on a January contract leaves a gap.
- Coverage and limits. Read each line for general liability, workers’ compensation, and auto. Note the dollar limits.
- Certificate holder and additional insured. The certificate holder is the party receiving the form. Confirm the building owner or association is named as the contract requires. Additional insured wording adds that party as an insured on the vendor’s liability policy, so ask for the endorsement, not just a checked box.
- Summary, not the policy. A certificate summarizes a policy and does not replace it. When a contract term depends on coverage, request the policy or endorsement itself.
Questions to Ask Before Signing a Day Porter Agreement
Ask how the vendor reports lapsed coverage, how it handles subcontractors, how it screens staff, and how it documents incidents.
- Coverage changes: How will you notify us if any required coverage is canceled or lapses, and how quickly?
- Subcontractors: Do you use subcontractors? If so, provide their proof of workers’ compensation. Florida law requires a contractor to require that evidence, under Fla. Stat. § 440.10. If a contractor becomes liable for the payment of compensation to a subcontractor’s employees because the subcontractor failed to secure such payment, the contractor may recover all benefits paid or payable, plus interest, from the subcontractor, unless the contractor and subcontractor have agreed in writing that the contractor will provide coverage.
- Chemicals and floors: Can you provide Safety Data Sheets for every cleaning product used here?
- Put service promises in the signed agreement, not only in a brochure.
Next Steps for a Building Manager Reviewing Vendor Paperwork
You may be reviewing a proposal you did not write. An owner or board may be waiting for your recommendation, and a renewal date may be close. That is a hard spot, and paperwork is where you can slow down and check.
Frequently asked questions
What day porter vendor insurance should a building require?
Most contracts call for general liability, workers’ compensation, and commercial auto when vehicles are used.
Is a certificate of insurance the same as a policy?
No. A certificate summarizes the policy, so request the policy or endorsement when a contract term depends on it.
Do day porter vendors on public contracts need E-Verify?
If you’re reviewing a specific day porter proposal for a South Florida building, our team can walk through it with you. Our contact page offers a free, confidential first consultation with no obligation to continue.
Questions to Ask Any Day Porter Vendor
Which policies do you carry?
Ask for a list of the coverage types in place today, including any that apply to vehicles or employees on site.
Can you send the policy or endorsement?
Request the underlying documents when your contract depends on a specific term, not just the summary certificate.
Who is covered on the policy?
Confirm the named insured and whether your property is listed as an additional insured where your contract requires it.
What happens when a policy renews?
Ask how renewal certificates will be delivered so your coverage records stay current through the life of the service agreement.
Have Questions About Your Day Porter Contract? Let's Talk.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.